How to Navigate the Mortgage Loan Origination Process Like a Pro

How to Navigate the Mortgage Loan Origination Process Like a Pro

Securing a mortgage loan is a significant financial step that requires careful navigation through a complex process. For professionals engaged in the lending industry, mastering the intricacies of the mortgage loan origination process is essential, especially when considering the potential challenges faced by borrowers (lendees). In this article, we will explore effective strategies for professionals to navigate the mortgage loan origination process seamlessly. Additionally, we will delve into the issues that borrowers might encounter during this journey.

A fundamental understanding of the mortgage loan origination process is the starting point for successfully guiding borrowers through the journey. The process encompasses several key stages that culminate in the approval and disbursement of the loan.

Application and Pre-Approval
 

Mortgage Loan Origination - approved

The process commences with potential borrowers seeking pre-approval from lenders. During pre-approval, the borrower’s financial stability, credit history, and income are evaluated to determine their eligibility for a loan. This initial step helps set realistic expectations and narrows down the options.

Documentation and Processing

Once pre-approved, borrowers complete the formal loan application. This step involves providing comprehensive personal and financial information, including tax returns, pay stubs, and other relevant documentation. The lender’s team then processes this information and verifies its accuracy.

Underwriting and Approval

The underwriting phase is where the lender assesses the borrower’s risk profile, analyzing their creditworthiness, financial history, and the value of the property they intend to purchase. This critical step determines whether the loan is approved and the terms under which it will be granted.

Closing and Disbursement

Upon approval, borrowers and representatives from the lending institution convene to finalize the loan agreement. This involves signing various legal documents and transferring ownership of the property. Subsequently, the funds are disbursed, marking the completion of the mortgage loan origination process.

While the mortgage loan origination process may appear straightforward, the devil often lies in the details. This is where modern solutions, such as loan servicing software, come into play, particularly for professionals engaged in lending and mortgage management. Loan servicing software offers a range of benefits that streamline the process and enhance the borrower’s experience.

Efficient Communication
Mortgage Loan Origination - communication

Effective communication is crucial in the mortgage loan origination process, involving multiple parties such as borrowers, lenders, real estate agents, and appraisers. Loan servicing software provides a centralized platform where all stakeholders can collaborate, share documents, and exchange vital information in real time. This seamless communication minimizes delays and ensures that everyone remains informed throughout the process.

Document Management
Mortgage Loan Origination - documentation

The mortgage origination process involves a substantial amount of documentation, from loan applications to property appraisals and legal agreements. Loan servicing software offers secure document storage and management capabilities, reducing the risk of lost paperwork and ensuring that all necessary documents are easily accessible when needed.

Automated Workflows

One of the challenges professionals face is managing the various steps involved in loan origination. Loan servicing software automates workflows, guiding users through each stage and prompting them to complete required tasks. This automation not only increases efficiency but also minimizes the risk of errors.

Transparency and Visibility

Borrowers often experience anxiety during the mortgage origination process due to uncertainty about the status of their application. Loan servicing software provides borrowers with transparency and visibility into the process. They can track the progress of their application, receive alerts, and stay informed about any additional information needed.

Potential Borrower Challenges

While professionals aim to guide borrowers through the mortgage loan origination process seamlessly, borrowers themselves might encounter certain challenges along the way.

Creditworthiness Hurdles
Mortgage Loan Origination - credit

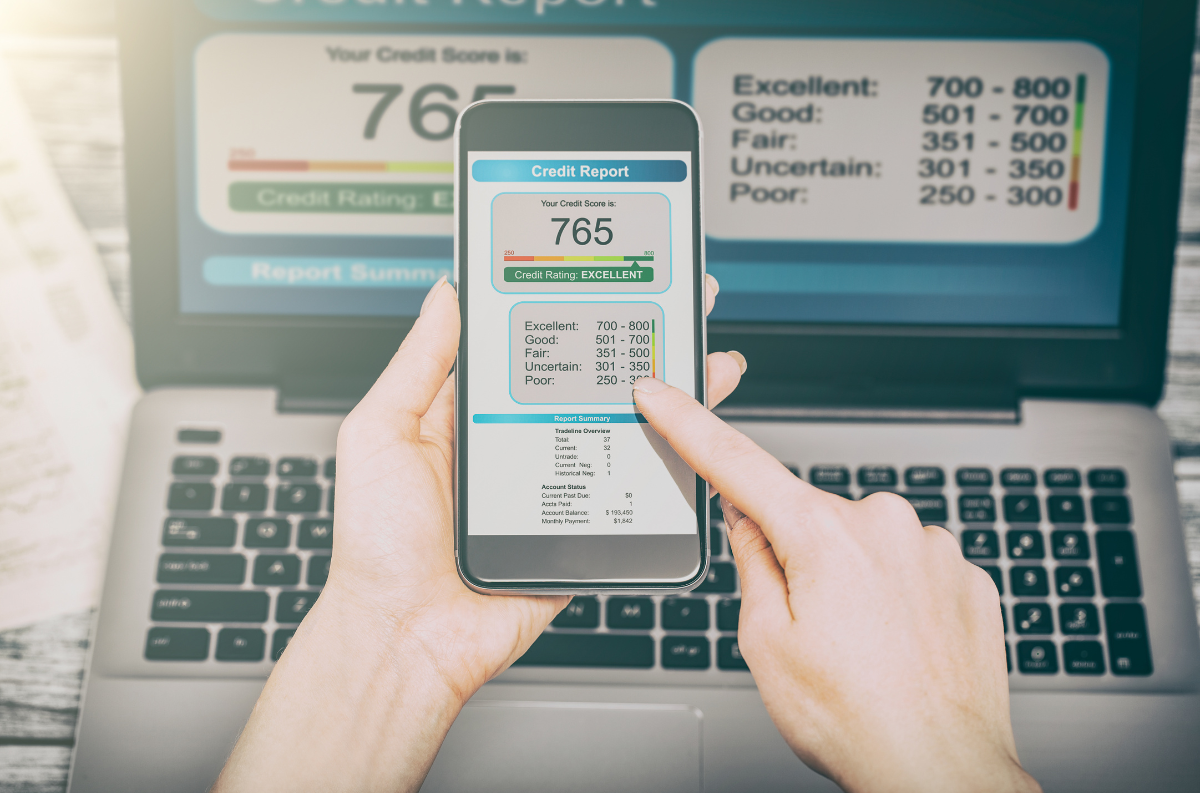
One of the primary obstacles borrowers face is related to creditworthiness. Lenders assess credit scores as part of the underwriting process, and borrowers with lower scores might encounter difficulties in securing favorable loan terms. Professionals should proactively educate borrowers about the importance of good credit and offer guidance on improving their credit profiles.

Documentation Demands

The mortgage origination process demands extensive documentation from borrowers. This can be overwhelming, especially for first-time homebuyers or those unfamiliar with the process. Professionals should anticipate this challenge and provide clear instructions and support to ensure that borrowers can provide the necessary paperwork accurately and promptly.

Complexity and Jargon
Mortgage Loan Origination - communication (2)

The mortgage industry comes with its own set of jargon and complex terminology that can confuse borrowers. Professionals must bridge this gap by explaining terms in simple language, ensuring that borrowers fully comprehend the details of their loan agreement.

Conclusion

In conclusion, navigating the mortgage loan origination process like a pro requires a combination of industry expertise, effective communication, and the right tools. Professionals in the lending industry can leverage loan servicing software to streamline workflows, enhance transparency, and provide borrowers with a smoother experience. While borrowers may face challenges during the process, knowledgeable professionals can guide them through credit hurdles, documentation demands, and complexities, ultimately leading to a successful mortgage origination journey.

Interested in learning more?

Visit our website, www.fundingo.com, to see what FUNDINGO can do for you.

 Have specific questions or want to talk to a FUNDINGO consulting expert?

 Contact us at info@fundingo.com
Fueling Dreams: Small Business Alternative Lending Strategies

Fueling Dreams: Small Business Alternative Lending Strategies

In today’s competitive business landscape, small businesses often find themselves in need of financial assistance to turn their dreams into reality. Traditional lending options may not always be accessible or feasible, leading many entrepreneurs to explore alternative lending strategies. In this article, we delve into the world of alternative lending and examine how it can fuel the dreams of small businesses.

Alternative lending offers innovative financing solutions beyond what traditional banks can provide. From online lenders to crowdfunding platforms, these alternative options offer flexibility and convenience, empowering entrepreneurs with the funds they need to grow and thrive.

In this highly informative piece, we explore different alternative lending strategies, including peer-to-peer lending, merchant cash advances, and invoice financing. We discuss the benefits and potential drawbacks of each option, allowing small business owners to make informed decisions that align with their unique goals and circumstances.

Whether you’re a budding entrepreneur or an established small business owner, understanding these alternative lending strategies can open up new avenues for growth and success. Join us as we uncover the secrets to fueling your dreams through alternative financing options.

Why small businesses seek alternative lending options


In today’s competitive business landscape, small businesses often find themselves in need of financial assistance to turn their dreams into reality. Traditional lending options may not always be accessible or feasible, leading many entrepreneurs to explore alternative lending strategies. In this article, we delve into the world of alternative lending and examine how it can fuel the dreams of small businesses.

Alternative lending offers innovative financing solutions beyond what traditional banks can provide. From online lenders to crowdfunding platforms, these alternative options offer flexibility and convenience, empowering entrepreneurs with the funds they need to grow and thrive.

Types of alternative lending strategies for small businesses

Small Business Alternative Lending Strategies - types

Small businesses often face unique challenges when it comes to securing funding. Traditional banks typically have strict lending criteria, making it difficult for small businesses with limited credit history or collateral to qualify for loans. Additionally, the lengthy approval process and paperwork involved can be a major deterrent for entrepreneurs who need quick access to funds.

Alternative lending options provide a lifeline for small businesses by offering more flexible eligibility requirements and faster approval times. These lenders understand the specific needs of small businesses and are willing to take on the risk that traditional banks may shy away from. Whether it’s a startup looking for seed capital or an established business in need of working capital, alternative lending options cater to a wide range of financing needs.

One popular alternative lending strategy is peer-to-peer lending, where individuals can lend money directly to small businesses through online platforms. This form of lending cuts out the middleman, allowing borrowers to access funds at competitive interest rates while providing investors with an opportunity to earn attractive returns.

Pros and cons of alternative lending for small businesses

Alternative lending encompasses a diverse range of strategies that cater to the unique needs of small businesses. One such strategy is merchant cash advances. This form of financing allows businesses to receive a lump sum payment in exchange for a percentage of their future credit card sales. It’s an attractive option for businesses with fluctuating cash flow as repayment is linked to revenue.

Another popular alternative lending strategy is invoice financing. This option allows businesses to access funds by selling their outstanding invoices to a lender at a discounted rate. It’s a great solution for businesses that experience delays in receiving payment from clients, as it provides immediate cash flow without waiting for invoices to be paid.

Crowdfunding has gained significant traction in recent years as a viable alternative lending strategy. Through online platforms, entrepreneurs can pitch their business ideas to a large pool of potential investors who contribute small amounts of money. This form of financing not only provides funds but also serves as a marketing tool, allowing businesses to generate buzz and gain exposure.

How to determine if alternative lending is right for your small business

Small Business Alternative Lending Strategies - strategy

As with any financing option, alternative lending strategies come with their own set of pros and cons. One major advantage is the accessibility and speed at which funds can be obtained. Unlike traditional banks, alternative lenders often have simplified application processes and faster approval times, allowing small businesses to seize opportunities without delay.

Flexibility is another key advantage of alternative lending. These options cater to businesses with varying needs and financial situations, offering tailored solutions that traditional banks may not be able to provide. Whether it’s a short-term loan, equipment financing, or a line of credit, alternative lenders offer a range of options to suit different business requirements.

However, alternative lending does come with some potential drawbacks. Interest rates and fees may be higher than those offered by traditional banks, reflecting the higher risk associated with lending to small businesses. It’s essential for business owners to carefully evaluate the costs involved and assess whether the benefits outweigh the expenses in their specific situation.

Steps to secure alternative lending for your small business

Steps

When considering alternative lending options, it’s crucial for small business owners to assess their specific needs and circumstances. Start by evaluating your current financial situation and determining how much funding you require. Consider the purpose of the loan and how it aligns with your business goals. Are you looking to invest in equipment, funding a marketing campaign, or bridging a cash flow gap?

Next, examine the eligibility requirements and terms of various alternative lending options. Some lenders may have specific criteria such as minimum revenue or credit score requirements. It’s important to ensure you meet these criteria before applying to avoid wasting time and effort.

Additionally, assess your ability to repay the loan. Look at your projected cash flow, revenue streams, and any potential risks that may impact your ability to make timely payments. Alternative lenders are often more lenient in their evaluation process, but it’s still crucial to ensure you can comfortably meet your repayment obligations.

Alternative lending platforms and resources

Once you’ve decided that alternative lending is the right choice for your small business, it’s time to take the necessary steps to secure the funding you need. Start by researching and comparing different alternative lenders to find the one that best suits your requirements. Look for reputable lenders with positive reviews and a track record of working with businesses similar to yours.

Prepare all the necessary documents and information required for the application process. This typically includes financial statements, tax returns, bank statements, and a business plan. Having these documents ready will streamline the application process and increase your chances of approval.

Before submitting your application, review it thoroughly to ensure accuracy and completeness. Mistakes or missing information can lead to delays or even rejection. Take the time to double-check all the details and make any necessary corrections before submitting your application.

Tips for successfully utilizing alternative lending for small businesses

Tips

There are several alternative lending platforms and resources available to small businesses seeking financing. These platforms leverage technology and data analytics to assess creditworthiness and provide fast funding decisions.

For businesses looking to leverage the power of crowdfunding, platforms like Kickstarter and Indiegogo offer a wide reach and access to a large pool of potential investors. These platforms provide a space for businesses to showcase their products or services and engage with backers who believe in their vision.

Additionally, government-backed programs like the Small Business Administration (SBA) offer alternative lending options through their loan guarantee programs. These programs provide additional security for lenders, making it easier for small businesses to access funds even if they don’t meet traditional lending criteria.

In Conclusion

To make the most of alternative lending strategies, small business owners should keep a few key tips in mind. First and foremost, it’s essential to have a clear understanding of your business’s financial needs and goals. By having a well-defined plan, you can identify the most appropriate alternative lending option for your specific situation.

Carefully review the terms and conditions of any financing agreement before accepting the funds. Pay close attention to interest rates, fees, repayment terms, and any potential penalties or hidden costs. It’s crucial to fully understand the financial implications and ensure they align with your business’s ability to repay the loan.

Maintaining open and transparent communication with your lender is also important. If you encounter any challenges or foresee any issues with repayment, it’s best to address them proactively. Many alternative lenders are willing to work with businesses to find solutions and avoid default.

Interested in learning more?

Visit our website, www.fundingo.com, to see what FUNDINGO can do for you.

 Have specific questions or want to talk to a FUNDINGO consulting expert?

 Contact us at info@fundingo.com
Private Loan Servicing Essentials: Managing Loans with Precision and Expertise

Private Loan Servicing Essentials: Managing Loans with Precision and Expertise

In this article, we will explore the key aspects of private loan servicing, including borrower communication, loan monitoring, collections, and reporting. Additionally, we will discuss the benefits of leveraging technology and software solutions to streamline the loan management process.

Whether you are a private loan servicing company looking to enhance your operations or a borrower seeking insights into how your loan is managed, this article will provide you with essential information and best practices to navigate the world of private loan servicing with precision and expertise.

Key Responsibilities of Private Loan Servicers


Private Loan Servicing - Tools

Private loan servicers play a vital role in the lending industry by managing loans on behalf of lenders. Their responsibilities include loan origination, record-keeping, payment processing, delinquency management, and regulatory compliance. Let’s explore each of these key responsibilities in detail.

Loan Origination

Loan origination is the process of creating and issuing a loan. Private loan servicers work closely with lenders to ensure that all necessary documentation is collected, reviewed, and approved. They also assess the creditworthiness of borrowers, verify income and employment details, and determine the loan terms and conditions. By handling the loan origination process with precision, private loan servicers set the foundation for a successful loan servicing journey.

Record-Keeping

Maintaining accurate and up-to-date loan records is crucial for private loan servicers. These records include borrower information, loan terms, payment history, and any modifications or changes made to the loan agreement. Effective record-keeping allows servicers to track loan performance, monitor repayments, and provide borrowers with accurate information about their loans. With the right tools and systems in place, private loan servicers can ensure that their records are comprehensive, organized, and easily accessible.

Payment Processing and Tracking

One of the primary responsibilities of private loan servicers is to manage loan payments. This involves collecting and processing payments from borrowers, allocating them correctly towards principal and interest, and providing borrowers with accurate statements. Private loan servicers use advanced payment processing systems to automate these tasks, minimizing the risk of errors and ensuring efficient payment tracking. By managing payments with precision, servicers can help borrowers stay on track with their loan obligations.

Delinquency Management and Collections

In some cases, borrowers may face difficulties in making their loan payments on time. Private loan servicers play a crucial role in managing delinquencies and collections. This involves contacting delinquent borrowers, understanding their financial situations, and working with them to find suitable solutions. Private loan servicers aim to minimize default rates by implementing effective collection strategies, such as setting up payment plans, offering loan modifications, or, in extreme cases, initiating foreclosure proceedings. With expertise in delinquency management, servicers can help borrowers overcome financial challenges while protecting the interests of lenders.

Regulatory Compliance in Private Loan Servicing

Compliance with legal and regulatory requirements is of utmost importance in private loan servicing. Private loan servicers mus-t stay updated with the ever-changing regulations governing the lending industry, such as the Truth in Lending Act (TILA), the Fair Debt Collection Practices Act (FDCPA), and the Real Estate Settlement Procedures Act (RESPA). By ensuring strict adherence to these regulations, servicers protect borrowers from unfair practices and maintain the integrity of the loan servicing process. Precision and expertise are crucial in navigating the complex landscape of regulatory compliance.

Essential Tools for Managing Loans

Private Loan Servicing - Essentials

To efficiently manage loans, private loan servicers rely on a range of tools and technologies. These tools help streamline processes, enhance communication, and improve overall efficiency. Let’s explore some essential tools that can help private loan servicers manage loans with precision and expertise.

Loan Management Software

Loan management software is a powerful tool that allows private loan servicers to automate and streamline various loan servicing tasks. These software solutions typically offer features such as loan origination, payment processing, record-keeping, delinquency management, and reporting. By centralizing loan data and automating repetitive tasks, loan management software helps servicers save time, reduce errors, and improve overall efficiency. Advanced reporting capabilities also provide valuable insights into loan performance, allowing servicers to make informed decisions and optimize their operations.

Customer Relationship Management (CRM) Systems

A CRM system is an essential tool for private loan servicers to effectively manage borrower communication. These systems enable servicers to track and record all interactions with borrowers, ensuring that important details and conversations are not overlooked. CRM systems also facilitate personalized communication, allowing servicers to send timely reminders, updates, and notifications to borrowers. By leveraging CRM systems, private loan servicers can maintain strong relationships with borrowers, enhance customer satisfaction, and improve overall loan servicing experience.

Document Management Systems

Efficient document management is crucial in private loan servicing, given the extensive paperwork involved. Document management systems allow servicers to store, organize, and retrieve loan-related documents securely. These systems offer features such as version control, document sharing, and electronic signatures, making it easier for servicers to manage loan documents throughout their lifecycle. With document management systems, private loan servicers can ensure compliance, reduce paperwork errors, and improve operational efficiency.

Loan Documentation and Record-Keeping

Accurate loan documentation and record-keeping are paramount in private loan servicing. Servicers must maintain comprehensive records of loan agreements, borrower information, payment history, and any modifications made to loan terms. These records serve as a reliable source of information for both borrowers and lenders and help ensure transparency and compliance. By leveraging loan management software and document management systems, private loan servicers can streamline the process of creating, organizing, and accessing loan documents, minimizing the risk of errors and improving overall efficiency.

Delinquency Management and Collections

Managing delinquencies and collections is an essential responsibility of private loan servicers. When borrowers fall behind on their loan payments, servicers must promptly address the issue and work with the borrower to find a suitable solution. Effective delinquency management involves early identification of delinquencies, proactive communication with borrowers, and the implementation of appropriate collection strategies. Private loan servicers should aim to help borrowers overcome financial difficulties while protecting the interests of lenders. By employing experienced collections teams and leveraging advanced delinquency management techniques, servicers can minimize default rates and optimize loan recovery.

Conclusion

Private loan servicing requires precision and expertise to effectively manage loans and ensure a smooth experience for both borrowers and lenders. By understanding the key responsibilities of private loan servicers and leveraging essential tools and technologies, servicers can streamline loan management processes, enhance communication, and improve overall efficiency. Whether a private loan servicer or a borrower seeking insights into loan management, the knowledge and best practices shared in this article will empower you to navigate the world of private loan servicing with precision and expertise.

Interested in learning more?

Visit our website, www.fundingo.com, to see what FUNDINGO can do for you.

 Have specific questions or want to talk to a FUNDINGO consulting expert?

 Contact us at info@fundingo.com
Transforming Loan Servicing with Innovative SaaS Solutions: A Comprehensive Exploration of the Underwriter Loan Process

Transforming Loan Servicing with Innovative SaaS Solutions: A Comprehensive Exploration of the Underwriter Loan Process

In the ever-evolving landscape of lending, efficiency and accuracy in loan servicing stand as the pillars of success. Among the myriad processes that underpin this crucial function, the underwriter loan process occupies a central position. This intricate dance involves meticulous evaluation, in-depth risk assessment, and ultimately, pivotal lending decisions. As the financial industry embraces the digital age, the introduction of Software-as-a-Service (SaaS) solutions has propelled the underwriter loan process into a new era, characterized by streamlined operations, heightened precision, and an unparalleled borrower journey. In this extensive article, we embark on an immersive journey through the underwriter loan process, dissecting each crucial stage with a magnifying lens, while unraveling the transformative impact of SaaS solutions in reshaping the very essence of loan servicing.

Unveiling the Underwriter Loan Process

Underwriter Process
At its core, the underwriter loan process represents an intricate choreography of steps that begins with the submission of a loan application and culminates in a decision that shapes financial destinies. To fully appreciate its significance, let’s delve deeper into the key stages that compose the underwriter loan process:

1. Application Review: The proverbial curtain rises as underwriters meticulously pore over loan applications. During this phase, the completeness and accuracy of the application are scrutinized, ensuring that no vital piece of information goes unnoticed.

2. Credit Analysis: The spotlight then shifts to the borrower’s credit history. Here, underwriters engage in a comprehensive analysis of credit reports, carefully examining payment patterns, credit utilization, and any historical delinquencies.

3. Income Verification: The financial prowess of the borrower takes center stage. Underwriters meticulously verify income details, sifting through pay stubs, tax returns, and employment records to ascertain the borrower’s capacity to repay the loan.

4. Collateral Evaluation: For loans anchored in collateral, this stage serves as a critical interlude. Underwriters embark on a thorough evaluation of the collateral’s value and condition, serving as a safeguard against potential default.

5. Risk Assessment: The underwriter’s role as a financial conductor comes to the fore. A comprehensive risk assessment takes place, encompassing a spectrum of variables, including credit risk, market conditions, and the borrower’s overall financial health.

6. Decision Making: The final crescendo arrives as underwriters weave together all the preceding elements. Drawing upon their expertise and the cumulative insights gained, a decision is rendered, determining the fate of the loan – approval, rejection, or possibly, an alternative proposition.

Empowering Loan Servicing through SaaS Solutions

Saas Undewriter loan process
In the era of technological advancements, the integration of SaaS solutions into the underwriter loan process has brought forth a new level of efficiency and sophistication.

Automated Document Verification

SaaS platforms introduce automation, relieving the need for manual data entry. This results in precise data accuracy, accelerates application reviews, and ensures a seamless borrower experience.

Advanced Analytics and Data Insights

SaaS solutions elevate the role of underwriters by providing access to a wealth of analytical capabilities. Through data insights, underwriters gain valuable information about borrower behavior, market trends, and risk assessment, equipping them with the necessary tools for informed decision-making.

Real-time Collaboration

SaaS platforms facilitate seamless communication and collaboration, creating a digital environment where underwriters and loan officers can interact in real time. With features like instant updates and centralized interactions, the process becomes smoother, minimizing any potential delays.

Holistic Risk Assessment

Embedded within SaaS tools are sophisticated algorithms that enable comprehensive risk assessment. By employing predictive modeling and scenario analyses, underwriters gain a panoramic view of potential risks. This empowers them with the ability to navigate the complexities of risk management with precision.

Tailored Workflow Flexibility

The adaptability of SaaS solutions is a notable advantage. Lenders can now design customized underwriting workflows that align with their specific needs. This flexibility enhances overall efficiency and accommodates a wide range of loan scenarios seamlessly.

Navigating Regulatory Compliance

The dynamic nature of regulatory requirements demands a harmonious blend of underwriting and compliance. SaaS platforms step up to the challenge by integrating compliance features that guide underwriters in adhering to the evolving standards, resulting in a well-coordinated compliance process.

The integration of SaaS solutions not only revolutionizes individual aspects of the loan servicing process but also fosters a harmonious orchestration of tasks. By seamlessly uniting automation, analytics, collaboration, risk assessment, tailored workflows, and compliance, SaaS solutions create a symphony of efficiency and effectiveness in loan underwriting. This transformative approach paves the way for a future where loan servicing reaches new heights of excellence in the ever-evolving landscape of finance and technology.

Unlocking Benefits for Loan Servicing Providers

Saas - Benefits
Unlocking Benefits for Loan Servicing Providers

In the domain of loan servicing, the integration of SaaS-driven underwriting emerges as a formidable companion for service providers, bringing a range of advantages:

Unparalleled Efficiency

SaaS solutions orchestrate a seamless fusion of streamlined workflows, orchestrating an elegant balance between automation and human expertise. This synergy reduces manual efforts, accelerating the loan processing tempo, resulting in tangible time and cost savings.

Elevated Customer Experiences

The swift underwriting process composes a narrative of borrower satisfaction. Swift loan approvals and improved terms create a melodic resonance that resonates with borrowers, nurturing loyalty and broadening the appeal to a wider audience.

Mitigated Risk

The SaaS-infused risk assessment script delivers a meticulous performance. Underwriters wield the precision of analytical tools, reducing the likelihood of extending loans to high-risk borrowers. This orchestrated composition contributes to a harmonious reduction in defaults.

Seamless Scalability

As the rhythm of loan volumes swells, SaaS solutions synchronize the pace. The architecture’s scalability empowers loan servicing providers to scale their operations harmoniously, ensuring a seamless expansion without any disruptions.

Competitive Edge

Equipped with SaaS-powered underwriting, loan servicing providers command a prominent position in the digital arena. The interplay of quicker approvals, improved terms, and an overall enhanced borrower experience crafts a distinctive melody that resonates strongly within the competitive landscape.

In Conclusion

The underwriter loan process, fortified by SaaS solutions, emerges as a symphony of precision and innovation, a harmonious blend of human expertise and technological virtuosity. As the financial industry marches boldly into the digital future, the underwriter loan process takes center stage, a testament to the potential of technology to redefine the contours of lending. SaaS-powered underwriting does not merely enhance operational efficiency; it transforms the very essence of loan servicing, offering a melody of accuracy, speed, and customer-centricity that will resonate for generations to come.

Interested in learning more?

Visit our website, www.fundingo.com, to see what FUNDINGO can do for you.

 Have specific questions or want to talk to a FUNDINGO consulting expert?

 Contact us at info@fundingo.com
Why KYC is Crucial for Private Lenders: Building Strong Relationships and Minimizing Fraud

Why KYC is Crucial for Private Lenders: Building Strong Relationships and Minimizing Fraud

In the fast-paced world of private lending, establishing trust and minimizing risk are paramount. That’s where KYC, or Know Your Customer, comes into play. KYC is not just an industry buzzword; it is a crucial process that private lenders must adhere to in order to build strong relationships with their clients and safeguard against fraud. This proactive approach involves gathering and verifying essential information about borrowers, such as their identity, financial history, and risk profile. By implementing KYC processes, private lenders can gain valuable insights into their clients, enabling them to make informed decisions and tailor their lending solutions accordingly. Furthermore, KYC acts as a robust defense mechanism, acting as a deterrent to potential fraudsters and protecting lenders from financial losses. In this article, we will explore the importance of KYC in the private lending industry and how it contributes to the overall growth and stability of lenders’ businesses. So, let’s delve into the world of KYC and discover why it is a crucial tool for private lenders.

The Importance of KYC for Private Lenders

Private lenders operate in an environment where trust and credibility are paramount. Unlike traditional banks, private lenders often have limited collateral and rely heavily on borrowers’ creditworthiness. Therefore, it is crucial for private lenders to have a comprehensive understanding of their customers to mitigate potential risks and make informed lending decisions.

KYC plays a pivotal role in this process by helping private lenders gather and verify crucial information about their customers. This includes verifying the identity of the borrower, assessing their financial history, evaluating their risk profile, and understanding their purpose for seeking a loan. By conducting a thorough KYC process, private lenders can ensure that they are dealing with legitimate borrowers and minimize the chances of lending to individuals involved in fraudulent activities.

Moreover, KYC enables private lenders to assess the creditworthiness of borrowers accurately. By analyzing a borrower’s financial history, including income, assets, and liabilities, private lenders can determine the borrower’s ability to repay the loan. This information helps lenders tailor their lending solutions, such as loan amounts, interest rates, and repayment terms, to match the borrower’s financial capacity, reducing the risk of default.

Overall, KYC is crucial for private lenders to build trust with their customers, make informed lending decisions, and mitigate the potential risks associated with lending in the private sector.

Building Strong Relationships Through KYC

KYC relationships

KYC is not only a regulatory requirement; it is also a powerful tool for private lenders to build strong and long-lasting relationships with their customers. By gathering comprehensive information about borrowers, lenders can gain valuable insights into their customers’ financial needs, goals, and preferences.

This knowledge allows lenders to offer personalized lending solutions tailored to the specific requirements of each borrower. For example, by understanding a borrower’s risk appetite, lenders can structure loan packages that offer flexible repayment options or lower interest rates. Such customized solutions not only strengthen the lender-borrower relationship but also increase the likelihood of repeat business and referrals.

Moreover, KYC enables private lenders to provide a seamless and efficient lending experience to their customers. By streamlining the information gathering and verification process, lenders can reduce the documentation burden on borrowers, making the loan application process faster and more convenient. This improves customer satisfaction and enhances the lender’s reputation as a trusted and customer-centric financial institution.

In summary, KYC is not only a compliance requirement but also a valuable tool for private lenders to build strong relationships with their customers. By understanding their customers’ needs and preferences, lenders can offer tailored lending solutions and provide a seamless lending experience, leading to increased customer loyalty and business growth.

How KYC Helps Minimize Fraud

KYC - minimize fraud

Fraud is a significant concern for private lenders, given the nature of their business and the limited collateral they often have. KYC acts as a robust defense mechanism against fraud, providing private lenders with the necessary safeguards to identify and prevent fraudulent activities.

By conducting a thorough KYC process, private lenders can identify potential red flags that may indicate fraudulent behavior. This includes verifying the authenticity of identification documents, cross-checking information provided by borrowers, and conducting background checks to ensure they are not involved in criminal activities.

Additionally, KYC helps private lenders assess the legitimacy of the borrower’s financial history. By analyzing the borrower’s credit report, income sources, and debt obligations, lenders can identify inconsistencies or discrepancies that may indicate fraudulent activity or misrepresentation.

Furthermore, KYC acts as a deterrent to potential fraudsters. The robust due diligence process involved in KYC sends a strong message that private lenders take their customers’ trust and the integrity of their lending operations seriously. Fraudsters are less likely to target lenders with stringent KYC processes, as the risk of being caught and facing legal consequences is significantly higher.

By minimizing the risk of fraud, private lenders can protect their businesses from financial losses, maintain their reputation in the market, and instill confidence in their customers and investors.

KYC Best Practices for Private Lenders

KYC Best Practices

To maximize the effectiveness of KYC processes, private lenders should adopt best practices that align with industry standards and regulatory requirements. Here are some key best practices to consider:

1. **Establish a comprehensive KYC policy**: Develop a robust KYC policy that outlines the procedures and processes to be followed by all employees involved in customer onboarding and due diligence. The policy should cover the identification and verification of customers, ongoing monitoring, record-keeping, and reporting suspicious activities.

2. **Implement a risk-based approach**: Private lenders should adopt a risk-based approach to KYC, focusing more resources and scrutiny on higher-risk customers. This includes conducting enhanced due diligence for customers who pose a higher risk of money laundering, terrorist financing, or other financial crimes.

3. **Invest in technology**: Leverage technology solutions to automate and streamline the KYC process. This includes using identity verification tools, data analytics, and artificial intelligence to enhance the accuracy and efficiency of customer due diligence. Technology can also help in ongoing monitoring of customer transactions for suspicious activities.

4. **Train employees**: Provide comprehensive training to employees involved in the KYC process to ensure they understand the importance of KYC, relevant regulations, and best practices. Regular training and updates will help employees stay informed about new risks and evolving regulatory requirements.

5. **Regularly update customer information**: Private lenders should have processes in place to regularly update customer information and conduct periodic reviews of customer due diligence. This ensures that the lender has the most up-to-date and accurate information about their customers and reduces the risk of lending to individuals involved in fraudulent activities.

By adopting these best practices, private lenders can enhance the effectiveness of their KYC processes, reduce the risk of fraud, and ensure compliance with regulatory requirements.

Implementing a KYC Process in Your Lending Business

KYC Processes

Implementing a robust KYC process in your lending business requires careful planning and execution. Here are some steps to consider:

1. **Develop a KYC policy**: Create a comprehensive KYC policy that outlines the procedures and processes to be followed by all employees involved in customer onboarding and due diligence. The policy should align with industry best practices and regulatory requirements.

2. **Establish customer identification procedures**: Define clear procedures for customer identification, including the documents and information required to verify the identity of borrowers. This may include government-issued identification documents, proof of address, and additional information based on the risk profile of the customer.

3. **Verify customer information**: Implement robust processes to verify the authenticity of customer-provided information. This may involve cross-checking information with reliable sources, conducting background checks, and using technology solutions for identity verification.

4. **Conduct ongoing monitoring**: Establish processes for ongoing monitoring of customer transactions to detect and report suspicious activities. This may involve setting up alerts and triggers based on predefined risk parameters and conducting periodic reviews of customer due diligence.

5. **Maintain accurate records**: Ensure that accurate and up-to-date records of customer due diligence are maintained. This includes maintaining copies of identification documents, transaction records, and any additional information collected during the KYC process.

6. **Regularly review and update the KYC process**: Continuously review and update your KYC process to ensure it remains effective and aligned with evolving regulatory requirements. Stay informed about new risks and industry best practices to enhance the effectiveness of your KYC process.

By following these steps, private lenders can implement a robust KYC process that helps build trust with customers, minimizes the risk of fraud, and ensures compliance with regulatory requirements.

Common Challenges in KYC Implementation and How to Overcome Them

Implementing a KYC process in the private lending industry comes with its own set of challenges. Here are some common challenges and strategies to overcome them:

1. **Balancing regulatory requirements and customer experience**: KYC processes can be time-consuming and may create friction in the customer onboarding process. Private lenders should strive to find a balance between meeting regulatory requirements and providing a smooth and efficient customer experience. This can be achieved by leveraging technology solutions to automate and streamline the KYC process, reducing the burden on customers while ensuring compliance.

2. **Data quality and reliability**: Private lenders heavily rely on accurate and reliable customer data for effective KYC. However, data quality issues, such as incomplete or outdated information, can hamper the effectiveness of the KYC process. Lenders should establish data validation and verification mechanisms to ensure the accuracy and reliability of customer data.

3. **Keeping up with evolving regulations**: KYC regulations are constantly evolving to address new risks and challenges in the financial industry. Private lenders should stay informed about regulatory updates and proactively update their KYC processes to ensure compliance. This may involve investing in regulatory intelligence tools or partnering with compliance experts to stay up to date with regulatory changes.

4. **Cost and resource constraints**: Implementing and maintaining a robust KYC process requires significant investment in technology, human resources, and training. Private lenders with limited resources may face challenges in allocating the necessary funds and expertise for KYC implementation. However, the cost of non-compliance and the potential impact of fraud justify the investment in KYC. Lenders can explore cost-effective solutions, such as outsourcing certain KYC functions or leveraging technology to streamline processes and reduce costs.

By addressing these challenges proactively, private lenders can ensure the successful implementation and maintenance of an effective KYC process.

KYC Tools and Technologies for Private Lenders

Technology plays a crucial role in streamlining and enhancing the effectiveness of KYC processes for private lenders. Here are some key tools and technologies that lenders can leverage:

1. **Identity verification solutions**: Identity verification tools use advanced algorithms and machine learning to verify the authenticity of identification documents provided by borrowers. These tools can detect forged or tampered documents, reducing the risk of identity theft and fraud.

2. **Data analytics and artificial intelligence**: Data analytics and artificial intelligence can be used to analyze customer data, identify patterns, and detect suspicious activities. These technologies can help lenders in ongoing monitoring of customer transactions and flag potential red flags for further investigation.

3. **Regulatory compliance software**: Regulatory compliance software helps private lenders stay up to date with changing regulations and automate compliance processes. These tools provide access to regulatory databases, monitor regulatory changes, and generate reports to ensure compliance with KYC requirements.

4. **Customer relationship management (CRM) systems**: CRM systems help lenders manage customer data, track customer interactions, and maintain accurate records of customer due diligence. These systems enable lenders to streamline customer onboarding, automate workflows, and provide a seamless customer experience.

5. **Blockchain technology**: Blockchain technology can enhance the security and integrity of KYC processes by providing a decentralized and transparent record of customer information. Blockchain-based KYC solutions enable secure sharing of customer data across multiple entities, reducing duplication of efforts and enhancing data privacy.

Private lenders should carefully evaluate their specific needs and requirements before selecting and implementing KYC tools and technologies. It is essential to ensure that the chosen solutions align with regulatory requirements and support the overall goals of the KYC process.

Conclusion: The Future of KYC in Private Lending

KYC is not just a compliance requirement; it is a crucial tool for private lenders to build trust with their customers, minimize fraud, and ensure the overall growth and stability of their businesses. As regulations continue to evolve, private lenders must stay proactive in adopting KYC best practices and leveraging technology to enhance their KYC processes.

The future of KYC in private lending lies in the seamless integration of technology, data analytics, and regulatory compliance. By embracing innovative solutions and industry best practices, private lenders can strengthen their customer relationships, minimize fraud risks, and maintain a competitive edge in the market.

In conclusion, KYC is not just a necessary process; it is a strategic advantage that private lenders can leverage to thrive in an increasingly complex and competitive lending landscape.

*Disclaimer: This article is for informational purposes only and does not constitute legal or financial advice. Private lenders should consult with legal and compliance professionals to ensure compliance with relevant regulations and best practices.*

Interested in learning more?

Visit our website, www.fundingo.com, to see what FUNDINGO can do for you.

 Have specific questions or want to talk to a FUNDINGO consulting expert?

 Contact us at info@fundingo.com