Benefits of Diversified Lending: How it Can Minimize Risk and Maximize Returns

Benefits of Diversified Lending: How it Can Minimize Risk and Maximize Returns

In today’s ever-changing financial landscape, diversification is key to minimizing risk and maximizing returns. One area where this holds particularly true is in lending. Diversified lending involves spreading your investments across different types of loans, borrowers, and industries. By doing so, you reduce the impact of any one loan or borrower defaulting, allowing you to achieve more consistent returns over time. But that’s not all. Diversified lending can also help you tap into new markets, expand your portfolio, and increase your overall profitability. In this article, we’ll explore the benefits of diversified lending in more detail, and show you how you can make it work for you. Whether you’re new to lending or a seasoned investor, this is one strategy you won’t want to miss. So read on and discover how you can minimize risk and maximize returns with diversified lending.

Understanding the Concept of Risk and Return
 

The future of loan origination_ what is ai

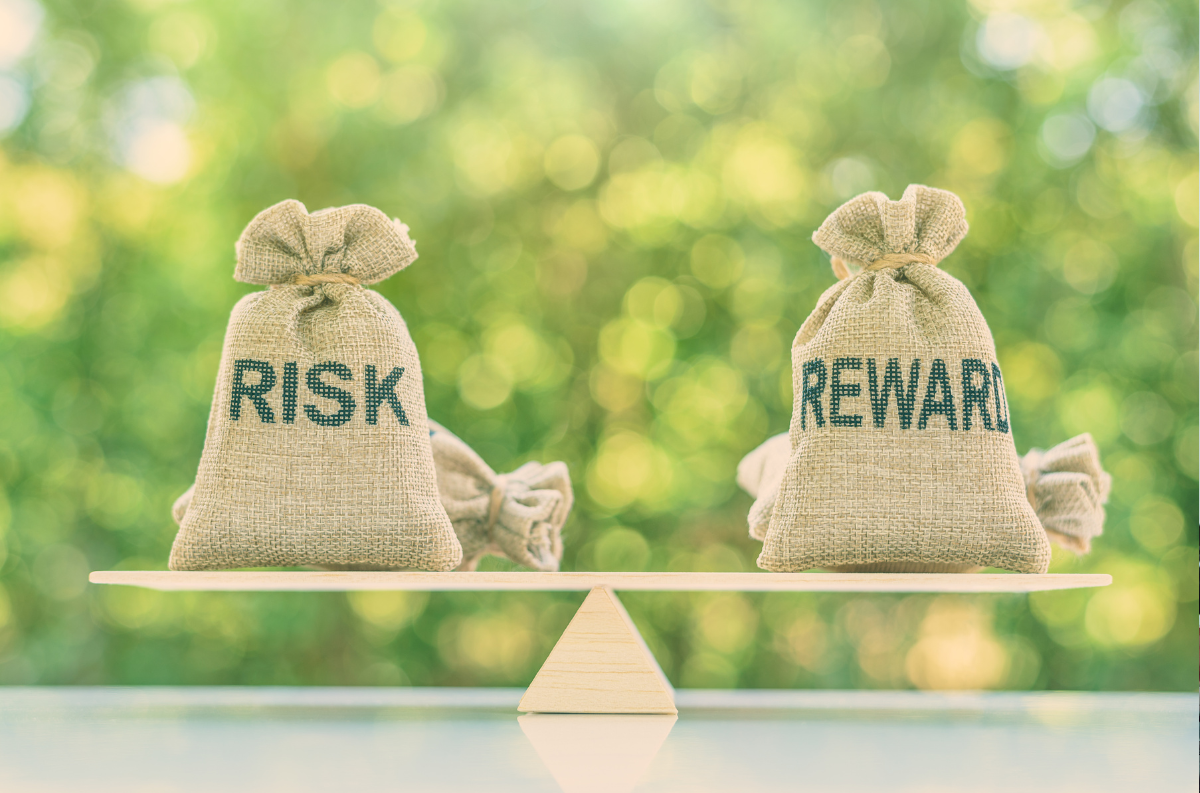
Before we dive into the benefits of diversified lending, we need to understand the concept of risk and return. When you invest in anything, including loans, there is always a certain amount of risk involved. The higher the risk, the higher the potential return, but also the higher the potential loss. Conversely, the lower the risk, the lower the potential return, but also the lower the potential loss.

This is where diversified lending comes in. By spreading your investments across different types of loans, borrowers, and industries, you reduce the impact of any one loan or borrower defaulting. This means that you can achieve more consistent returns over time, without having to take on excessive risk.

Another key benefit of diversified lending is that it allows you to tap into new markets and industries that you may not have access to otherwise. This can help you expand your portfolio and increase your overall profitability.

The Benefits of Diversified Lending
The future of loan origination_ benefits

So, what are the specific benefits of diversified lending? Let’s take a closer look.

Minimizes Risk

As mentioned earlier, diversified lending helps minimize risk by spreading your investments across different types of loans, borrowers, and industries. This means that if one loan or borrower defaults, it won’t have a significant impact on your overall portfolio. By reducing the impact of any one default, you can achieve more consistent returns over time, without having to take on excessive risk.

Maximizes Returns

Diversified lending can also help maximize returns. By tapping into new markets and industries, you can take advantage of opportunities that you may not have access to otherwise. This can help you expand your portfolio and increase your overall profitability.

Provides a Steady Stream of Income

Diversified lending can also provide a steady stream of income. By investing in a variety of loans, you can receive regular payments from multiple sources. This can help you generate a consistent stream of income, which can be particularly beneficial for retirees or those looking to supplement their existing income.
Ex

Examples of Diversified Lending Strategies
The future of loan origination_ role of humans

Now that we’ve explored the benefits of diversified lending, let’s take a look at some specific strategies you can use to implement this approach.

Peer-to-Peer Lending

One popular strategy for diversified lending is peer-to-peer (P2P) lending. P2P lending platforms connect borrowers with investors, allowing you to invest in a variety of loans across different industries and borrowers. By investing in a variety of loans, you can spread your risk and achieve more consistent returns over time.

Real Estate Crowdfunding

Another strategy for diversified lending is real estate crowdfunding. Real estate crowdfunding platforms allow you to invest in a variety of real estate projects across different geographies and property types. By investing in a diverse range of projects, you can spread your risk and achieve more consistent returns over time.

Direct Lending

Direct lending is another popular strategy for diversified lending. This involves investing directly in loans to small businesses or individuals. By investing in a variety of loans, you can spread your risk and achieve more consistent returns over time.
How

How to Implement a Diversified Lending Strategy
The future of loan origination_ togetherness

Now that you understand the benefits of diversified lending and some specific strategies you can use, let’s take a look at how you can actually implement a diversified lending strategy.

Determine Your Risk Tolerance

The first step in implementing a diversified lending strategy is to determine your risk tolerance. This will help you identify the types of loans and borrowers that are right for you. If you have a low risk tolerance, you may want to focus on lower-risk loans, such as those with a high credit rating. If you have a higher risk tolerance, you may want to consider higher-risk loans, such as those to start-ups or small businesses.

Choose Your Platform

The next step is to choose your platform. There are a variety of platforms available for diversified lending, including P2P lending platforms, real estate crowdfunding platforms, and direct lending platforms. Do your research and choose a platform that aligns with your goals and risk tolerance.

Diversify Your Investments

Once you’ve chosen your platform, it’s time to start diversifying your investments. This means investing in a variety of loans, borrowers, and industries. By spreading your investments across different types of loans, borrowers, and industries, you reduce the impact of any one loan or borrower defaulting, allowing you to achieve more consistent returns over time.
Risk

Risks Associated with Diversified Lending

While diversified lending can help minimize risk and maximize returns, it’s important to be aware of the risks involved. Here are some of the key risks associated with diversified lending:

Default Risk

One of the biggest risks associated with diversified lending is default risk. While spreading your investments across different types of loans, borrowers, and industries can help reduce the impact of any one default, there is still a risk that multiple defaults could occur at once, resulting in significant losses.

Market Risk

Another risk to be aware of is market risk. If the overall market experiences a downturn, your portfolio could be negatively impacted, regardless of how diversified it is.

Platform Risk

Finally, there is also platform risk to consider. If the platform you’re investing through experiences financial difficulties or goes bankrupt, your investments could be at risk.

Monitoring and Managing a Diversified Lending Portfolio

To minimize the risks associated with diversified lending, it’s important to actively monitor and manage your portfolio. Here are some key steps you can take:

Regularly Review Your Investments

Make sure to regularly review your investments to ensure they are performing as expected. If you notice any red flags, such as an increase in defaults or a decline in returns, take action to address the issue.

Rebalance Your Portfolio

Another key step is to rebalance your portfolio on a regular basis. This means adjusting your investments to ensure they are aligned with your risk tolerance and goals.

Stay Up-to-Date on Market Trends

Finally, it’s important to stay up-to-date on market trends and industry developments. This can help you identify new opportunities and make informed investment decisions.

Tools and Resources for Diversified Lending
The future of loan origination_ togetherness

If you’re interested in implementing a diversified lending strategy, there are a variety of tools and resources available to help you get started. Here are a few to consider:

Lending Platforms

There are a variety of lending platforms available for P2P lending, real estate crowdfunding, and direct lending. Do your research and choose a platform that aligns with your goals and risk tolerance.

Investment Advisors

Investment advisors can provide valuable guidance and advice on how to implement a diversified lending strategy. Look for an advisor who has experience with this approach and a track record of success.

Online Resources

There are also a variety of online resources available, including blogs, forums, and educational materials. Take advantage of these resources to learn more about diversified lending and how to implement this approach.

Conclusion on the Importance of Diversified Lending for Investors

Diversified lending is a powerful strategy for minimizing risk and maximizing returns. By spreading your investments across different types of loans, borrowers, and industries, you can achieve more consistent returns over time, while also tapping into new markets and expanding your portfolio. While there are risks involved, these can be minimized through careful monitoring and management of your portfolio. If you’re interested in implementing a diversified lending strategy, there are a variety of tools and resources available to help you get started. So don’t wait – start exploring the benefits of diversified lending today!

Interested in learning more?

Visit our website, www.fundingo.com, to see what FUNDINGO can do for you.

 Have specific questions or want to talk to a FUNDINGO consulting expert?

 Contact us at info@fundingo.com
How AI Can Revolutionize Commercial Lending: Unlocking the Potential for Growth

How AI Can Revolutionize Commercial Lending: Unlocking the Potential for Growth

In today’s rapidly evolving business landscape, commercial lending institutions are continually seeking ways to enhance their lending processes and improve decision-making. Artificial Intelligence (AI) has emerged as a transformative technology with the potential to revolutionize commercial lending. By harnessing the power of AI, lenders can streamline operations, gain deeper insights, and make more accurate credit assessments. In this article, we will explore the various ways AI can boost commercial lending, from automating repetitive tasks to improving risk management and enhancing customer experiences.

Automating Repetitive Tasks

Commercial lending involves numerous repetitive tasks, such as data entry, document verification, and financial statement analysis. These tasks are time-consuming and prone to human errors. However, AI-powered automation can eliminate these inefficiencies by automating these processes. Machine Learning algorithms can extract relevant data from financial statements, tax returns, and other documents, enabling quick and accurate analysis. This automation not only saves time and resources but also reduces the risk of errors, ensuring greater efficiency in loan processing.

In addition to saving time and reducing errors, AI-powered automation in commercial lending brings other significant benefits to the table. One such advantage is scalability. As the volume of loan applications and transactions increases, lenders can rely on AI automation to handle the growing workload without the need to scale up their workforce proportionally. This scalability allows lenders to efficiently manage peak periods, such as when launching new loan products or during economic upturns, when loan demand is high.

Enhanced Credit Assessment and Risk Management

AI commercial lending - risk management

Accurate credit assessment is a critical aspect of commercial lending. AI algorithms can analyze vast amounts of data from multiple sources, such as financial records, credit scores, industry trends, and macroeconomic indicators, to evaluate the creditworthiness of borrowers. By leveraging this data, AI systems can generate more accurate credit risk models, leading to improved decision-making and reduced default rates. AI can also monitor the loan portfolio in real-time, detecting early warning signs of potential defaults and enabling proactive risk management strategies. Here’s how enhanced credit assessment and risk management with AI can benefit commercial lending:

Comprehensive Data Analysis: AI algorithms can analyze a wide range of data sources, including financial statements, tax returns, credit scores, and industry trends. By leveraging this data, AI systems gain a holistic view of the borrower’s financial health, enabling lenders to make more informed lending decisions. AI can identify patterns, trends, and correlations within the data that human operators may overlook, leading to more accurate credit assessments.

Improved Risk Prediction: With the ability to analyze extensive data sets, AI algorithms can predict credit risks more accurately. By identifying risk factors and evaluating their impact on loan repayment, AI systems generate risk scores and models that reflect the borrower’s creditworthiness. This predictive capability allows lenders to assess the likelihood of default and adjust loan terms accordingly, minimizing potential losses and optimizing risk-adjusted returns.

Enhanced Fraud Detection: AI algorithms can identify suspicious patterns and anomalies within borrower data, helping lenders detect potential fraudulent activities. By analyzing historical data, transaction patterns, and other relevant information, AI systems can flag applications that exhibit signs of fraud, protecting lenders from financial losses and reputational damage.

Mitigation of Bias: AI-powered credit assessment and risk management solutions can help reduce bias in lending decisions. By relying on data-driven analysis, AI algorithms base their assessments on objective criteria rather than subjective judgments. This can lead to fairer and more inclusive lending practices, ensuring that credit decisions are based on merit and borrowers are not discriminated against due to personal biases.

Advanced Predictive Analytics

AI commercial lending - analytics

AI enables lenders to utilize advanced predictive analytics to forecast borrower behavior, market trends, and potential risks. By analyzing historical data and patterns, AI algorithms can predict market fluctuations, interest rate movements, and industry-specific risks. This empowers lenders to make informed decisions, develop proactive strategies, and adjust loan terms accordingly. Predictive analytics also assists in identifying opportunities for cross-selling and upselling financial products to existing clients, optimizing revenue generation for lending institutions. Here are some examples of how lenders can benefit from advanced analytics produced by AI:

Accurate Forecasting: AI algorithms can analyze vast amounts of historical data, including borrower information, economic indicators, market trends, and industry-specific data. By identifying patterns and correlations within the data, predictive analytics can generate accurate forecasts for market fluctuations, interest rate movements, and industry-specific risks. This empowers lenders to make informed decisions, proactively adjust lending strategies, and optimize loan terms to align with market conditions.

Risk Mitigation: Predictive analytics can help lenders identify potential risks and anticipate borrower behavior. By analyzing historical data and patterns, AI algorithms can identify early warning signs of potential defaults or credit deterioration. This allows lenders to take proactive measures to mitigate risks, such as restructuring loans, offering assistance programs, or implementing risk mitigation strategies. By identifying potential risks in advance, lenders can reduce default rates, minimize losses, and optimize their loan portfolios.

Enhanced Cross-Selling and Upselling: Predictive analytics enables lenders to identify opportunities for cross-selling and upselling financial products to existing clients. By analyzing borrower data, spending patterns, and creditworthiness, AI algorithms can identify specific financial needs and recommend relevant products or services. This not only increases revenue generation for lending institutions but also strengthens customer relationships.

Improved Customer Experience

what is a loan origination system

AI-powered chatbots and virtual assistants are transforming the customer experience in commercial lending. Chatbots can handle routine customer inquiries, provide real-time support, and guide borrowers through the loan application process. Virtual assistants leverage natural language processing to engage with borrowers in more interactive and personalized conversations. These AI-driven interactions provide borrowers with 24/7 support, streamline the application process, and enhance overall customer satisfaction.

Fraud Detection and Prevention

AI commercial lending - fraud

Commercial lending is susceptible to various forms of fraudulent activities. AI-based fraud detection systems employ advanced algorithms to analyze historical and real-time data, identify patterns, and detect anomalies. By leveraging AI, lenders can detect suspicious activities, flag potential fraudulent applications, and mitigate financial risks. This proactive approach not only protects lenders from losses but also enhances the overall security and trust in the lending process.

Conclusion

AI is revolutionizing the commercial lending landscape by introducing automation, enhancing risk management, improving decision-making, and elevating customer experiences. Lenders who embrace AI technologies can gain a competitive edge by streamlining operations, reducing costs, and offering superior services. As AI continues to evolve, its potential to transform commercial lending will only grow, empowering lenders to make smarter, data-driven decisions and facilitating the growth of businesses through access to timely and efficient financing solutions.

In the ever-changing world of commercial lending, embracing AI is not just an option; it is an opportunity for lenders to lead the way and unlock new possibilities for growth.

Interested in learning more?

Visit our website, www.fundingo.com, to see what FUNDINGO can do for you.

 Have specific questions or want to talk to a FUNDINGO consulting expert?

 Contact us at info@fundingo.com
Top 5 Pain Points For Loan Servicing

Top 5 Pain Points For Loan Servicing

Loan servicing plays a critical role in the financial industry, ensuring the smooth management of loans throughout their lifecycle. However, it is not without its challenges. In this article, we will explore the top five pain points for loan servicing and provide valuable insights and strategies to overcome them. Whether you are a financial institution or a loan servicing provider, understanding and addressing these pain points will help optimize your processes and enhance customer satisfaction.

Delinquency Management: Effective Strategies for Timely Resolution

One of the primary pain points in loan servicing is managing delinquencies. Late payments and defaults can have a significant impact on the lender’s revenue and borrower relationships. To address this, implement a proactive approach by leveraging advanced data analytics to identify early warning signs. By closely monitoring payment patterns and borrower behavior, you can detect potential delinquencies and take appropriate action promptly. Additionally, establish clear communication channels to reach out to borrowers, offering support and providing options for repayment plans or loan modifications.

Regularly analyze and assess the effectiveness of your delinquency management strategies to identify areas for improvement. Continuously update and refine your processes based on industry best practices and evolving borrower needs. By prioritizing proactive delinquency management and employing effective strategies for timely resolution, you can mitigate risks, minimize losses, and maintain a healthy loan portfolio.

Loan Modification Processes: Streamlining for Efficiency

Modification process

Loan modification processes often present challenges for both lenders and borrowers. To streamline these processes, leverage technology solutions that automate and simplify the documentation and approval workflows. Implement an online platform where borrowers can submit modification requests and upload necessary documents securely. This reduces manual paperwork, improves efficiency, and accelerates the decision-making process. Emphasize clear communication and transparency throughout the loan modification process, ensuring borrowers are informed about the status and progress of their requests.

Continuous evaluation and improvement of the loan modification processes are essential. Analyze data and metrics to identify bottlenecks or areas for optimization, and be open to feedback from both borrowers and staff involved in the process. By regularly reviewing and refining your loan modification processes, you can enhance efficiency, improve borrower satisfaction, and increase the overall success rate of loan modifications.

Default and Foreclosure Prevention: Proactive Measures for Mitigation

Modification process

Default and foreclosure are significant concerns for loan servicers. Implement preventive measures to minimize the occurrence of defaults. Develop early intervention strategies by closely monitoring borrowers who exhibit signs of financial distress. Promptly reach out to these borrowers to understand their challenges and explore alternatives to default, such as loan restructuring or forbearance options. Proactively engage in financial counseling and education programs to equip borrowers with the knowledge and tools to manage their loans responsibly.

Develop comprehensive default prevention strategies that encompass loan modification options, repayment plans, and assistance programs. Provide borrowers with clear information about these options and guide them through the process of applying for assistance. Additionally, consider collaborating with local community organizations or nonprofits that specialize in foreclosure prevention to expand your reach and provide additional support to borrowers facing financial hardships.

Regularly evaluate the effectiveness of your default and foreclosure prevention measures by analyzing data and tracking outcomes. Identify patterns and trends to refine your strategies and ensure continuous improvement.

Customer Communication and Support: Building Trust and Transparency

trust

Effective customer communication and support are vital in loan servicing. Establish clear lines of communication through various channels, including phone, email, and online platforms. Regularly update borrowers on their account status, upcoming payments, and any changes to loan terms or policies. Implement a responsive customer service team to promptly address borrower inquiries and concerns. By providing timely and accurate information, you foster trust, enhance borrower satisfaction, and minimize potential disputes.

Regularly communicate with borrowers about their repayment progress and provide support in case of financial difficulties. Be proactive in offering alternative payment arrangements, hardship programs, or loan modification options when appropriate. This demonstrates a commitment to helping borrowers succeed and can significantly reduce the likelihood of defaults or foreclosures.

Technology Integration and Automation: Optimizing Loan Servicing Processes

innovation

To overcome the challenges faced by loan servicers, integrating technology and automation is essential. Implement a robust loan servicing system that centralizes data, streamlines workflows, and ensures regulatory compliance. Leverage artificial intelligence and machine learning algorithms to analyze borrower data and identify patterns, enabling proactive decision-making. Automate routine tasks such as payment processing, document management, and reporting to improve operational efficiency and reduce errors.

However, it’s important to strike a balance between automation and personalized customer interactions. While automation improves operational efficiency, human interaction remains crucial for providing exceptional customer service and handling complex inquiries. Maintain a customer-centric approach by ensuring that borrowers have access to support and assistance when needed, either through direct interactions with customer service representatives or through technology-enabled channels such as live chat or email.

Regularly evaluate the effectiveness of technology integration and automation by monitoring key performance indicators and soliciting feedback from both borrowers and internal teams. Continuously refine and update your technology infrastructure to stay current with industry trends and evolving borrower expectations.

By harnessing the power of technology and automation, loan servicers can optimize their processes, enhance operational efficiency, and deliver a seamless borrower experience while ensuring compliance with regulatory requirements.

Conclusion

Loan servicing can be a complex and challenging process, but by understanding and addressing the pain points involved, lenders and loan servicing providers can optimize their operations and provide an enhanced borrower experience. Proactive delinquency management, streamlined loan modification processes, effective default prevention, transparent customer communication, and technology integration are crucial for success in loan servicing. By implementing these strategies, financial institutions can navigate these pain points effectively and drive better outcomes for both lenders and borrowers.

Remember, loan servicing is a dynamic field, and staying updated with industry trends and regulations is essential. Continuously monitor and adapt your practices to meet the evolving needs of borrowers and regulatory requirements. By prioritizing customer satisfaction, leveraging technology, and employing proactive strategies, loan servicing can become a smoother and more efficient process, benefiting all stakeholders involved.

Interested in learning more?

Visit our website, www.fundingo.com, to see what FUNDINGO can do for you.

 Have specific questions or want to talk to a FUNDINGO consulting expert?

 Contact us at info@fundingo.com
Revolutionize or perish: The private loan servicing predicament

Revolutionize or perish: The private loan servicing predicament

In the rapidly evolving landscape of private loan servicing, financial institutions are facing a critical predicament: adapt and revolutionize their loan servicing practices or risk falling behind. Traditional loan servicing methods are becoming outdated and ineffective in meeting the demands of today’s borrowers. To remain competitive and relevant, private loan servicers must embrace innovation, leverage advanced technologies, and prioritize customer-centric approaches. In this article, we will explore the challenges faced by private loan servicers, the need for revolutionizing loan servicing practices, and the benefits that come with embracing change.

The Challenges of Traditional Loan Servicing

Private loan servicers often grapple with a range of challenges when relying on traditional loan servicing practices. Manual processes, paper-based documentation, and siloed systems create inefficiencies and hinder the ability to deliver exceptional borrower experiences. Limited automation leads to increased processing times, higher error rates, and reduced scalability. Moreover, outdated communication channels and lack of transparency create frustration and erode borrower trust. These challenges not only impede operational efficiency but also hinder the growth and competitiveness of private loan servicers.

The Need for Revolutionizing Loan Servicing Practices

Revolutionize Private Loan Servicing - Practices

To address the shortcomings of traditional loan servicing, private loan servicers must undergo a revolution in their practices. Revolutionizing loan servicing involves embracing innovative technologies, streamlining processes, and prioritizing customer-centric approaches. By doing so, private loan servicers can unlock numerous benefits and gain a competitive edge in the market.

In addition to the benefits gained by private loan servicers through revolutionizing loan servicing practices, there are significant advantages for borrowers as well. A customer-centric approach coupled with innovative technologies and streamlined processes leads to a more seamless and transparent borrowing experience. Borrowers can benefit from faster loan approvals, quicker access to funds, and improved communication throughout the loan servicing journey. With self-service options, borrowers have greater control over their accounts, enabling them to manage their loans conveniently and efficiently. Revolutionizing loan servicing practices ultimately empowers borrowers by providing them with a higher level of service, enhanced convenience, and a sense of trust and confidence in their loan servicer. By placing the borrower at the forefront of their operations, private loan servicers not only strengthen their relationships with borrowers but also foster loyalty and positive word-of-mouth referrals, contributing to long-term success in the competitive lending market.

Embracing Innovative Technologies

Revolutionize Private Loan Servicing - embracing tech

Adopting innovative technologies is a crucial aspect of revolutionizing loan servicing practices. Advanced loan servicing software and platforms offer features such as automation, artificial intelligence, and data analytics. Automation eliminates manual tasks, reduces errors, and speeds up the loan servicing process. Artificial intelligence can enhance decision-making and enable personalized borrower experiences. Data analytics provides valuable insights into loan performance, borrower behavior, and risk assessment, enabling informed decision-making and proactive strategies. By leveraging these technologies, private loan servicers can streamline operations, enhance efficiency, and deliver superior borrower experiences.

The adoption of innovative technologies in loan servicing not only improves efficiency and borrower experiences but also has a positive impact on risk management. Advanced loan servicing software and platforms enable private loan servicers to leverage data analytics and artificial intelligence to assess and mitigate risks effectively. By analyzing borrower data, loan performance trends, and market indicators, loan servicers can identify potential red flags and take proactive measures to address them. This proactive risk management approach helps reduce delinquencies, defaults, and potential losses for both the loan servicer and the borrower. Additionally, the use of advanced technologies in loan servicing allows for real-time monitoring and alerts, enabling loan servicers to detect and respond to potential risks promptly. By embracing innovative technologies, private loan servicers can enhance risk management practices and maintain a healthy loan portfolio while providing a secure and reliable lending environment for borrowers.

Streamlining Processes

Revolutionize Private Loan Servicing - streamline

Streamlining processes is another key component of revolutionizing loan servicing practices. By evaluating existing workflows and identifying bottlenecks, inefficiencies, and manual workarounds, private loan servicers can streamline operations and reduce costs. Standardizing processes, automating repetitive tasks, and implementing workflow management tools can improve efficiency, accuracy, and scalability. Additionally, streamlining processes allows for faster loan approvals, quicker disbursements, and better borrower satisfaction.

In addition to improving efficiency and borrower satisfaction, streamlining processes in loan servicing has a direct impact on cost savings and resource optimization. By identifying and eliminating redundant or unnecessary steps in the loan servicing workflow, private loan servicers can significantly reduce operational costs. Automation and standardization of processes enable the efficient allocation of resources, reducing the need for manual intervention and minimizing the potential for errors. This, in turn, frees up valuable staff time, allowing loan servicers to redirect their focus towards higher-value tasks such as personalized borrower support and strategic decision-making. Moreover, streamlined processes enable quicker loan approvals and disbursements, reducing the time borrowers have to wait for their funds. The faster and more seamless the loan servicing process, the higher the borrower satisfaction levels, which can lead to increased customer loyalty and positive referrals. By streamlining processes, private loan servicers can achieve cost efficiencies, optimize resource allocation, and deliver a superior borrower experience, ultimately strengthening their position in the competitive loan servicing landscape.

Prioritizing Customer-Centric Approaches

Revolutionize Private Loan Servicing - customer

A customer-centric approach is essential in revolutionizing loan servicing practices. Private loan servicers must put borrowers at the center of their operations and strive to deliver exceptional borrower experiences. This involves adopting user-friendly digital platforms for loan applications and account management, providing transparent and timely communication, and offering personalized support. By leveraging technology to enable self-service options, borrowers gain convenience and control over their loan servicing experience. Investing in borrower education and financial literacy programs also demonstrates a commitment to helping borrowers succeed and builds long-term relationships.

Benefits of Revolutionizing Loan Servicing Practices

Revolutionize Private Loan Servicing - benefits

Revolutionizing loan servicing practices brings numerous benefits for private loan servicers. By embracing innovation, private loan servicers can enhance operational efficiency, reduce costs, and improve risk management. Automation and advanced technologies eliminate manual errors and accelerate processing times, leading to increased productivity and scalability. Additionally, revolutionizing loan servicing practices enhances borrower satisfaction, loyalty, and retention. Improved borrower experiences result in positive word-of-mouth referrals, increased borrower acquisition, and a strengthened market position.

In Conclusion

Private loan servicers face a critical choice: revolutionize their loan servicing practices or risk becoming obsolete in a rapidly evolving industry. The challenges of traditional loan servicing can be overcome by embracing innovative technologies, streamlining processes.  If you need help improving your loan servicing system, let us know!

Interested in learning more?

Visit our website, www.fundingo.com, to see what FUNDINGO can do for you.

 Have specific questions or want to talk to a FUNDINGO consulting expert?

 Contact us at info@fundingo.com
Simplify Your Loan Origination System for Maximum Efficiency

Simplify Your Loan Origination System for Maximum Efficiency

Financial institutions that offer new loan products often face challenges when it comes to servicing those loans. One primary reason for this struggle is that traditional loan management solutions are not equipped to handle the complexities of new or bespoke lending products. To address this issue, it is crucial for lenders to simplify their loan origination systems and optimize efficiency. By streamlining processes, leveraging advanced technology, and adopting a borrower-centric approach, lenders can enhance their loan origination capabilities and provide a seamless experience to borrowers. In this article, we will explore the importance of simplifying your loan origination system and how it can lead to maximum efficiency.

Understanding the Challenges of Traditional Loan Management Solutions


Simply Loan Origination System - Challenges

Traditional loan management solutions have long been the go-to option for financial institutions to handle loan origination. However, these systems often fall short when it comes to managing new or bespoke lending products. These products may have unique requirements, complex structures, or specific eligibility criteria that cannot be accommodated by rigid, one-size-fits-all solutions. As a result, lenders struggle with manual workarounds, inefficient processes, and increased risk of errors.

The Limitations of Manual Workarounds

Financial institutions that rely on manual workarounds to handle new loan products face numerous challenges. Manual processes are time-consuming, error-prone, and hinder scalability. The need for multiple data entry points and manual verification of information can lead to inconsistencies and delays in loan origination. This not only affects operational efficiency but also negatively impacts the borrower experience. Lengthy processing times and potential errors can frustrate borrowers and harm the institution’s reputation.

The Power of Simplification

Simply Loan Origination System - Simplify

To overcome these challenges, lenders need to simplify their loan origination systems. By doing so, they can optimize efficiency, improve data accuracy, and enhance the overall borrower experience. Simplification involves streamlining processes, adopting advanced technology solutions, and embracing a borrower-centric approach.

Streamlining processes is a fundamental step in simplifying the loan origination system. It requires a comprehensive review of existing workflows to identify bottlenecks, redundant steps, and areas for improvement. By eliminating unnecessary complexities and standardizing processes, lenders can achieve greater efficiency. For example, developing standardized templates for loan applications, documentation requirements, and underwriting procedures can streamline the review and approval process. This not only reduces errors but also ensures consistency across loan applications.

Adopting Advanced Technology Solutions

LOS - Real Estate Lending - analytic

The adoption of advanced technology solutions is crucial for simplifying the loan origination system and maximizing efficiency. Loan origination systems equipped with features like automation, data integration, and customizable workflows can significantly enhance the loan origination process. Automation can eliminate manual tasks, such as data entry and document generation, reducing errors and saving time. Data integration allows for seamless information exchange across systems, improving data accuracy and reducing duplicate data entry. Customizable workflows enable lenders to tailor the loan origination process to their specific needs and lending products, ensuring efficient and consistent loan origination.

Embracing a Borrower-Centric Approach

A borrower-centric approach is essential in simplifying the loan origination system. By placing the borrower at the center of the process, lenders can create a seamless and personalized experience. This includes offering user-friendly online application portals, clear and transparent communication, and proactive borrower support. A borrower-centric approach not only enhances the borrower experience but also improves operational efficiency. By providing borrowers with self-service options, such as online document submission and real-time application status updates, lenders can reduce manual efforts and speed up the loan origination process.

The Role of Data Analytics

LOS - Real Estate Lending - audit

Data analytics plays a crucial role in simplifying the loan origination system and optimizing efficiency. By leveraging the power of data, lenders can gain actionable insights, improve decision-making, and identify areas for improvement. Data analytics can provide lenders with a comprehensive view of their loan origination processes, enabling them to identify bottlenecks, measure performance metrics, and make data-driven decisions. By analyzing loan origination data, lenders can identify patterns, trends, and potential risks, allowing for proactive risk mitigation strategies.

In Conclusion

Financial institutions that offer new loan products face challenges when it comes to servicing those loans, mainly due to limitations in traditional loan management solutions. Simplifying the loan origination system is crucial for maximizing efficiency and addressing these challenges. By streamlining processes, adopting advanced technology solutions, embracing a borrower-centric approach, and leveraging data analytics, lenders can enhance their loan origination capabilities and provide a seamless experience to borrowers. Simplifying the loan origination system not only improves operational efficiency but also enhances the borrower experience, reduces errors, and increases scalability. In an ever-evolving lending landscape, financial institutions must prioritize simplification to stay competitive and meet the evolving needs of borrowers and the industry.

Interested in learning more?

Visit our website, www.fundingo.com, to see what FUNDINGO can do for you.

 Have specific questions or want to talk to a FUNDINGO consulting expert?

 Contact us at info@fundingo.com